GLOBAL SITUATIONAL SNAPSHOT – EXECUTIVE DASHBOARD
WEEK 23 / 2026 FORECAST
Business • Geopolitics • Life
Europe • DACH • CEE Focus
A) EXECUTIVE SUMMARY (30 Seconds)
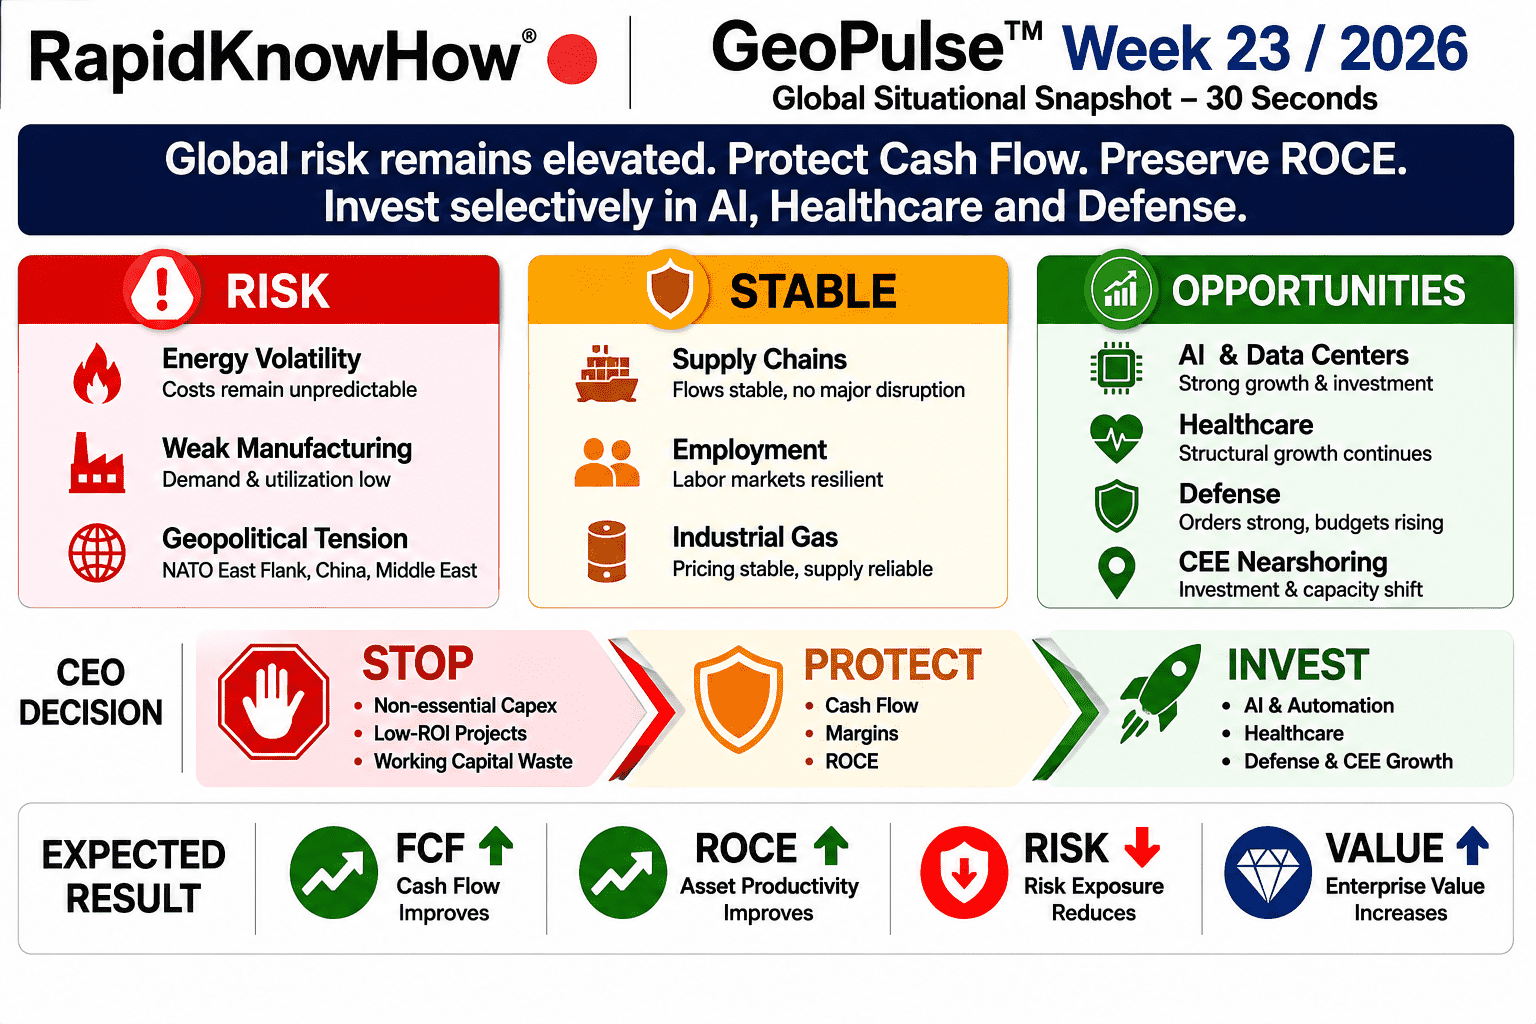
GLOBAL STATUS
🟠 CAUTION
The world economy remains stable but fragile.
Three dominant forces continue shaping the environment:
- Geopolitical fragmentation
- Industrial competitiveness pressure
- AI-driven capital reallocation
For CEOs and investors, the key theme remains:
Protect Cash Flow → Preserve ROCE → Invest Selectively
B) EISENHOWER EXECUTIVE MATRIX
| Priority | Topic | Impact | Action |
|---|---|---|---|
| 🔴 DO NOW | Energy Cost Volatility | Very High | Protect margins |
| 🔴 DO NOW | Supply Chain Resilience | Very High | Dual sourcing |
| 🔴 DO NOW | AI Productivity Gap | Very High | Accelerate AI adoption |
| 🟠 SCHEDULE | Manufacturing Optimization | High | Improve utilization |
| 🟠 SCHEDULE | Workforce Upskilling | High | AI competencies |
| 🟡 DELEGATE | Administrative Digitization | Medium | Automate |
| 🟢 MONITOR | Consumer Confidence | Medium | Watch |
C) WHAT CHANGED SINCE LAST WEEK?
↑ Increased
Geopolitical Risk
- NATO eastern flank remains sensitive.
- Black Sea logistics risk remains elevated.
Industrial Competition
- European competitiveness concerns intensified.
- Pressure from US and Asian manufacturing continues.
AI Investment
- Capital continues shifting toward AI infrastructure.
↓ Improved
Energy Supply
- No major disruption observed.
- Storage levels remain supportive.
Supply Chain
- Container flows remain stable.
- Freight bottlenecks limited.
↔ Unchanged
Europe
- Weak growth.
- High energy costs.
- Manufacturing pressure.
D) GLOBAL BUSINESS HEATMAP
| Sector | Status | Trend |
|---|---|---|
| Defense | 🟢 Strong | Up |
| AI Infrastructure | 🟢 Strong | Up |
| Data Centers | 🟢 Strong | Up |
| Healthcare | 🟢 Strong | Up |
| Logistics | 🟠 Stable | Flat |
| Industrial Gas | 🟠 Stable | Flat |
| Automotive | 🟠 Weak | Flat |
| Chemicals | 🔴 Weak | Down |
| Steel | 🔴 Weak | Down |
E) EUROPE / DACH / CEE FOCUS
🇩🇪 Germany
Status
🔴 Weak
Issues:
- Automotive pressure
- Chemical industry weakness
- High energy costs
Outlook
Weak stabilization.
🇦🇹 Austria
Status
🟠 Stable
Strengths:
- Services
- Tourism
- Specialized manufacturing
Risk:
- German slowdown
🇨🇭 Switzerland
Status
🟢 Strong
Strengths:
- Healthcare
- Pharma
- Financial Services
🇵🇱 Poland
Status
🟢 Strong
Benefiting from:
- Nearshoring
- Logistics
- Defense investments
🇨🇿 Czech Republic
Status
🟠 Stable
Dependent on:
- German industrial demand
🇸🇰 Slovakia
Status
🟠 Stable
Risk:
- Automotive exposure
🇭🇺 Hungary
Status
🟠 Stable
Risk:
- Energy dependence
F) NET CASH-FLOW IMPACT LENS
ENERGY
0–30 Days
| Factor | Impact |
|---|---|
| Electricity | 🔴 Negative |
| Gas | 🟠 Neutral |
| Oil | 🟠 Neutral |
Actions
✓ Hedge exposure
✓ Improve efficiency
RED FLAG
🚨 TTF Gas +25% combined with Brent >105 USD
Expected effect:
- FCF deterioration
- Margin pressure
- ROCE decline
SUPPLY CHAIN
0–30 Days
| Factor | Impact |
|---|---|
| Freight | 🟢 Positive |
| Ports | 🟢 Stable |
| Inventory | 🟠 Neutral |
Actions
✓ Dual sourcing
✓ CEE supplier development
MANUFACTURING
0–30 Days
| Factor | Impact |
|---|---|
| Capacity Utilization | 🔴 Negative |
| Labor Cost | 🟠 Neutral |
| Automation | 🟢 Positive |
Actions
✓ Improve utilization
✓ Reduce working capital
✓ Focus on productivity
G) ROCE DELTA ESTIMATOR
| Sector | Expected ROCE Impact |
|---|---|
| AI Infrastructure | 🔺 +2% to +5% |
| Defense | 🔺 +1% to +3% |
| Healthcare | 🔺 +1% to +2% |
| Logistics | ↔ 0% to +1% |
| Industrial Gas | ↔ 0% to -2% |
| Automotive | 🔻 -1% to -3% |
| Chemicals | 🔻 -2% to -4% |
H) INDUSTRIAL GAS (IGAS) DEEP DIVE
Pricing
Current Situation
🟠 Stable
Large suppliers continue disciplined pricing.
No major price war visible.
Energy Input Costs
| Item | Status |
|---|---|
| Electricity | 🔴 Elevated |
| Natural Gas | 🟠 Moderate |
| Diesel | 🟠 Moderate |
Implication
Energy remains the biggest margin lever.
Supply Reliability
Status
🟢 Good
No major shortage signals.
Customer Demand
Strong
🟢 Healthcare
🟢 Electronics
🟢 Food & Beverage
🟢 Data Centers
Weak
🔴 Chemicals
🔴 Steel
🔴 Heavy Industry
Margin Outlook
0–30 Days
🟠 Stable
30–90 Days
🟢 Slight Improvement
If energy costs remain under control.
I) IGAS CEO PLAYBOOK
Priority 1
Protect Energy Margin
Priority 2
Increase Contract Indexation
Priority 3
Focus on Growth Segments
✓ Healthcare
✓ Electronics
✓ Data Centers
✓ Defense
Priority 4
Reduce Working Capital
✓ Cylinder utilization
✓ Fleet utilization
✓ Inventory reduction
Priority 5
Improve ROCE
Target:
ROCE > 20%
through asset productivity rather than volume growth.
J) LIFE DASHBOARD
| Indicator | Status |
|---|---|
| Employment | 🟢 Stable |
| Inflation | 🟠 Moderate |
| Housing | 🟠 Weak |
| Travel | 🟢 Strong |
| Healthcare | 🟢 Strong |
| AI Impact on Jobs | 🔺 Accelerating |
K) TOP 5 OPPORTUNITIES (NEXT 90 DAYS)
- AI Productivity Programs
- Defense Supply Chains
- Data Center Expansion
- Healthcare Investments
- Nearshoring into CEE
L) TOP 5 RISKS (NEXT 90 DAYS)
- Energy Cost Shock
- Geopolitical Escalation
- Manufacturing Weakness
- Chemical Sector Recession
- Delayed AI Adoption
M) RAPIDKNOWHOW CEO CONCLUSION
Global Risk Level
🟠 Elevated but Manageable
Europe Outlook
🟠 Weak but Stabilizing
DACH Outlook
🟠 Cautious
CEE Outlook
🟢 More Attractive than Western Europe
Industrial Gas Outlook
🟠 Stable with Selective Growth Opportunities
CEO Action for Week 23
Protect Cash Flow → Improve Asset Productivity → Preserve ROCE → Invest Selectively in AI, Healthcare, Defense and Data Centers.
RapidKnowHow® GeoPulse™ Week 23 / 2026
Mastering Global Opportunities with GeoPower Intelligence 🔴