Turn ONE cash opportunity into ONE verified cash result.
The objective is to improve cash generation at ONE site without weakening safety, availability, quality or customer value. The buying organization leads implementation. RapidKnowHow® provides neutral know-how, business cases and tools; users apply the actions and verify their results.
ONE operating formula
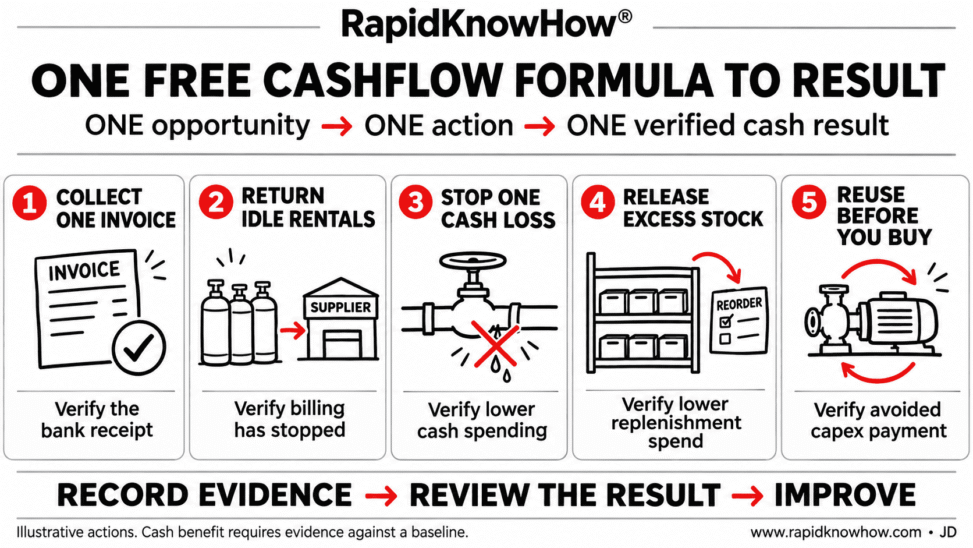
ONE URGENT PROBLEM → ONE OBJECTIVE → ONE ACTION → RECORD EVIDENCE → REVIEW THE RESULT → IMPROVE
Choose one opportunity, appoint one accountable owner, record a baseline and review date, then act. An estimate becomes a verified result only when evidence supports a cash difference attributable to that action.
For this report, FCF = net cash from operating activities − capital expenditure paid. FCF definitions vary, so keep this definition consistent across the baseline and result. The SEC describes this common calculation and the need for a clear definition and reconciliation [1].
Incremental FCF for the review period = change in operating cash flow attributable to the action − change in capex paid attributable to the action.
Compare actual results with a credible no-action baseline for the same period. Account for implementation payments, cash taxes, volume and price changes, working capital, displaced costs and any offsetting effects. Do not add working-capital release a second time if it is already included in operating cash flow.
Top 5 ONE Free Cashflow Actions to Result
This is a suggested starting sequence for an industrial SME, not an empirical ranking by return. Prioritize using your own expected net cash impact, speed, effort and operating risk. Every amount below is illustrative, pre-tax and unverified. Examples are separate cases, not an additive business case.
1. Collect ONE overdue invoice
Owner: Finance / accounts receivable, supported by the account owner.
ONE action: Select an undisputed overdue invoice for completed work. Resolve the remaining documentation block and agree a payment date.
Example: A €5,000 invoice is received earlier than it would have been without the action. This accelerates cash and releases working capital; it creates no new revenue. If both payment dates fall within the same reporting period, the period-end FCF difference may be zero. Deduct any collection fee or discount.
Evidence: Original invoice, due date, documented expected payment date and matched bank receipt.
Verified result: Cash received earlier, with timing and net amount established.
2. Return ONE batch of idle rented assets
Owner: Procurement / site logistics.
ONE action: Reconcile the rental invoice with physical cylinder or equipment records. Return a verified idle batch under the agreed contract terms.
Example: 20 cylinders × €8 monthly rent = €160 avoided for a full month. Less €40 return cost gives €120 pre-tax cash benefit for that month, assuming the reduced payment occurs in that period. A partial month or notice period changes the result.
Evidence: Physical register, contract, signed return receipt, billing stop confirmation, corrected bill and lower payment.
Verified result: Rental cash outflow falls while required supply availability is maintained.
3. Stop ONE recurring cash loss
Owner: Operations / maintenance.
ONE action: Measure one gas leak or recurring waste source and arrange a safe correction by qualified staff.
Example: Avoiding 100 Nm³ at €2/Nm³ reduces purchased gas by €200 over 30 days. Less a €50 repair payment gives €150 pre-tax benefit if cash purchasing falls in the period.
Evidence: Comparable meter readings and production data, repair bill, purchase records and payment evidence. Normalize for output, operating hours, prices and stock movements.
Verified result: Lower measured loss leads to lower cash expenditure. Lower consumption alone remains potential if a fixed contract charge or existing stock prevents a payment reduction.
4. Release ONE excess-stock position
Owner: Supply chain / inventory planning.
ONE action: Select one item above its justified safety stock. Consume usable excess stock and reduce or cancel replenishment within agreed supplier terms.
Example: €1,000 less purchasing paid, less €100 implementation cost, releases €900 pre-tax cash in the review period, assuming no offsetting effects.
Evidence: Stock and demand records, revised order, supplier agreement, lower payment and unchanged service level.
Verified result: Less cash remains tied up in inventory. Record this as a one-time working-capital release; do not claim the same stock reduction again next month. A stock write-down alone releases no cash. ACCA explains how inventory and receivables affect the cash operating cycle [2].
5. Reuse ONE asset before buying
Owner: Operations / capital expenditure owner.
ONE action: Check whether suitable idle equipment can perform the required job before committing to a new purchase. Verify fitness, capacity, safe use and alternative uses.
Example: Avoid a documented €4,000 capex payment that would otherwise occur in the review period. Deduct €600 redeployment cost: €3,400 pre-tax cash benefit, before any other effects.
Evidence: Approved purchase baseline, cancellation, redeployment cost, commissioning record and payment reconciliation.
Verified result: The required job is delivered with lower cash spending. Distinguish permanent purchase avoidance from a payment merely deferred to a later period. Do not count the same benefit as both lower operating cost and avoided capex.
ONE verification record
Record: site | problem | owner | action | baseline and assumptions | period | expected cash benefit | actual cash difference | implementation cost | tax and other adjustments | evidence | reviewer | next action.
Use three clear statuses: Potential → Implemented → Verified. A missing bank or payable record leaves the result pending. An annualized estimate stays separate from cash realized to date.
ONE immediate action
At ONE industrial-gas site, reconcile ONE cylinder-rental invoice with the physical register. Identify ONE idle batch, check return terms and arrange its return. Verify that rental billing and cash payments actually fall.
Repeat only after reviewing the first result.
RapidKnowHow® — Knowledge is useless unless it improves someone’s life.
www.rapidknowhow.com • JD
Sources
[1] SEC, Non-GAAP Financial Measures, Question 102.07: https://www.sec.gov/rules-regulations/staff-guidance/corporation-finance-interpretations/non-gaap-financial-measures
[2] ACCA, Working capital management: https://www.accaglobal.com/gb/en/student/exam-support-resources/fundamentals-exams-study-resources/f9/technical-articles/wcm.html
RapidKnowHow® — THE DECISION COMPANY™
Industrial Gas Leadership 2030
PROVE VALUE. THEN SCALE.
Watch the 60-second roadmap: 10 strategic actions for DACH and CEE, 2026–2030.
Start with ONE customer challenge. Use the Industrial Gas Action Guide to turn your first action into a measurable result.
RapidKnowHow® — Leading Industrial Gas Opportunity Signal Identifier in DACH & CEE